FILE / Finance
How to Use Sinking Funds to Handle Irregular Expenses
Unexpected annual bills can wreck a monthly plan, but sinking funds turn those irregular expenses into predictable, bite‑size savings goals. Learn how to spot nonmonthly costs, spread them across the year, and plug realistic sinking fund amounts into a household budget.
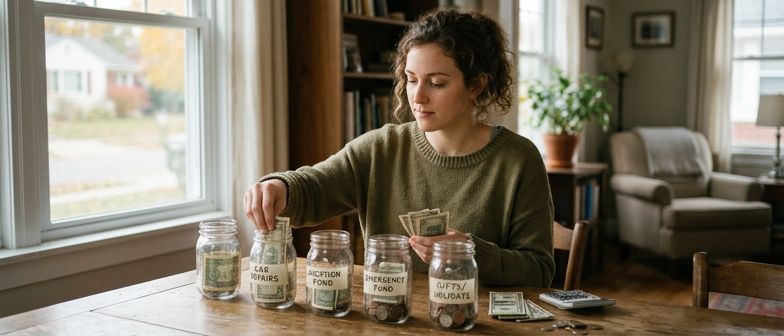
What Sinking Funds Are and How They Tackle Irregular Expenses
A sinking fund is a savings bucket you build up over time for a specific, expected cost, such as car insurance, property taxes, or a yearly subscription. Instead of scrambling when these irregular bills arrive, you set aside a small amount from each paycheck inside your household budget, either in one account with a tracking tool or in several clearly labeled accounts. Many budgeting guides describe these funds as planned savings that turn large, infrequent expenses into manageable monthly contributions so they feel like routine bills rather than surprises. This helps smooth spending throughout the year and prevents big payments from colliding with everyday needs such as groceries, fuel, or rent.
Sinking funds differ from an emergency fund because they cover costs you can reasonably predict rather than unexpected events. An emergency reserve is usually kept for situations such as a sudden job loss or an unforeseen medical issue, while a sinking fund might be used for a planned vacation or an annual membership fee. By forecasting these irregular expenses and setting money aside on a schedule, households may reduce reliance on credit cards or last minute cuts to other priorities. Introductory money management resources often encourage separating planned savings from emergency reserves so it is clear how each dollar in the budget is intended to be used.
Spotting Irregular Expenses Before They Surprise You
Irregular costs are bills that do not appear every month but recur over the year, such as insurance premiums, car registration, holiday travel, or membership dues. People often feel caught off guard because they only review a short period of bank activity instead of a full year. A useful first step is to pull 12 months of checking and card statements and highlight charges that did not repeat each month but are likely to return, like an annual streaming service, school fees, or vet visits. This backward review uses your own history instead of guesswork and helps build a realistic list of nonmonthly expenses.
Once this list is ready, turn it into a simple forecast so these costs become planned instead of surprising. Note the name of each bill, the month it usually falls, and the most recent amount, then add up what is due in each month across the next year. For each bill, subtract the amount already reserved and divide the remainder by the number of saving periods before its due date. Dividing by twelve only works when you have a full year to prepare. Reviewing this list at least annually and checking against updated notices from insurers, utilities, and membership organizations keeps your household budget aligned with current due dates and prices.
Building a Simple Expense Forecasting List
To build a simple forecast for irregular expenses, review the last 12 months of bank and card statements and note any costs that do not appear every month, such as insurance premiums, car registration, school supplies, or holiday travel. Estimate each bill and subtract money already reserved, then divide the remainder by the months before it is due, and add these figures together so you know how much to set aside in your household budget as planned savings for sinking funds. Revisit this list at least once a year to reflect price changes or shifts in your situation, and compare it with general money management guidance from reliable consumer education sources without treating that information as personalized financial advice.
How to Set Up and Fund Your Sinking Funds
To set up sinking funds, start by listing irregular costs that tend to surprise you, such as car registration, insurance premiums, school supplies, or holiday travel. Review at least the last 12 months of bank and card statements to spot charges that do not occur every month but follow a pattern. Once you have your list, group similar items into a few categories, like car costs, medical bills, or celebrations, so your household budget tracks several clear funds instead of many tiny ones.
Decide where to keep this money so it stays separate from daily spending but is available when needed. Some people open a dedicated savings account or several labeled sub‑accounts at the same bank for each category. Others keep one main savings account and use a spreadsheet or budgeting app to track how much of the balance is reserved for each sinking fund. Multiple accounts can make goals easy to see, while a single account is simpler to manage but requires more discipline not to spend what is set aside for future bills.
Calculate how much to move into each fund every pay period so your planned savings line up with upcoming expenses. Estimate what you expect to spend in a year for each category and divide by 12 for monthly contributions, or by the number of paychecks if you are paid weekly or every other week. As a fictional example, a $600 bill with twelve months to save and no money already reserved requires $50 per month. If it is due in three months, the same starting position requires $200 per month. These amounts are examples, not insurance quotes. Automating transfers through your bank or budgeting app can help you stay consistent, and you can adjust the amounts as your estimates improve.
Examples of Monthly Contributions for Common Funds
One way to handle irregular expenses is to take an annual bill, such as an insurance premium, and break it into monthly pieces. If you have a full year before the bill is due, divide the amount still needed by twelve, and move that amount into a separate savings space each month. When the renewal date arrives, the money is already set aside and your regular household budget stays steady.
Fitting Sinking Funds Into Your Household Budget
To fit sinking funds into your household budget, first list irregular costs for the next year, such as vehicle registration, annual subscriptions, or planned home maintenance. Total each category, then divide by the number of paychecks before the bill is due so the amount becomes a manageable monthly or biweekly line in your plan. Budget tools that highlight planned savings and irregular bills often suggest treating these transfers like fixed expenses alongside rent, utilities, and groceries, which helps prevent skipping them when cash feels tight.
When income or prices change, review your expense forecast before dropping these savings entirely. Rank upcoming costs by urgency and impact, giving priority to car insurance, essential medical care, and similar obligations over holidays or optional travel. You can temporarily shrink contributions to lower‑priority items while keeping at least small payments toward essentials, then restore them as your situation improves. Checking your categories each month and comparing planned versus actual amounts helps you see patterns, make trade‑offs deliberately, and keep irregular expenses from disrupting your overall budget.
Q&A
-
What is a sinking fund for irregular expenses?
A sinking fund is money set aside for a specific future cost, such as insurance, car repairs, or holiday travel. Saving smaller amounts regularly turns a large, occasional bill into a planned item instead of a surprise. -
How do I find expenses that belong in sinking funds?
Review about a year of bank and card statements and highlight charges that appear a few times a year, like annual bills, school costs, or memberships. Any nonmonthly cost that tends to repeat can be placed in a separate savings pot. -
How can I forecast these occasional bills?
List each expected irregular cost, subtract funds already reserved, then divide each remainder by the saving periods before its due date. Add these amounts together to see how much of your income should be reserved as planned savings. -
What does funding one annual bill look like in practice?
In a fictional example with a full twelve months to prepare, a $600 premium requires $50 each month into a labeled savings account. When the bill arrives, the money is ready and your regular budget does not need a large adjustment. -
How do I fit these savings into a household budget?
Treat transfers into sinking funds like fixed bills. Decide how much you must have saved by each due date, divide by the number of paychecks, and add that figure to your budget. If it feels tight, reduce lower‑priority spending so the plan is workable.